Secret Santa for 100 or more employees
For 100 employees, run two to four department groups of 50 or fewer, with one shared budget, one policy and one date. That keeps each group inside the free limit, each reveal short and each organizer in charge of a manageable list. Or run one group with the Office plan, $39 once per event, which covers up to 300 people and emails each person their link. Total gift spend is about $2,500 at $25 each.
The numbers for 100
| Item | Value |
|---|---|
| People | 100 |
| Budget each at $25 | $25 (about $2,500 total) |
| Gifts to open | 100 |
| Groups | 2 to 4 free department groups of 25 to 50, or one Office plan group ($39 once per event) |
| Organizers | 1 per group, 1 lead for the company |
| Ideal timeline | 5 weeks |
Worked example: who pays what
Take 100 employees, 80 of whom join, with a $25 gift each. The table compares three ways to fund it. The company-paid rows use the Publication 15-B rule that cash and cash equivalents are never de minimis; the last row is the usual office arrangement.
| Funding | Gift spend for 80 people | Tax treatment (IRS Publication 15-B, 2026) |
|---|---|---|
| Each giver pays for the gift they buy | $2,000, paid by the 80 employees | The company provides nothing, so there is no company fringe benefit to track |
| Company buys a non-cash treat box per person | $2,000, paid by the company | Under IRS fringe benefit rules, a holiday gift other than cash, with a low fair market value, can be de minimis.1 |
| Company reimburses gift cards or cash | $2,000, paid by the company | Under IRS fringe benefit rules, cash and cash equivalent benefits such as gift cards, no matter how little, are not excludable as a de minimis benefit.2 |
| Platform cost, either way | $0 for groups of 50 or fewer; $39 once for one Office plan group | Not an employee benefit; a company expense |
Split by department or location
- By department: friends and teammates draw each other, so the reveal is fun.
- By floor or office: easier delivery.
- Across departments: a cross-team draw mixes people but needs more organizing.
- Keep one budget. The same amount for every group keeps it fair.
Company-level plan
- Announce one policy and one budget for the company. Adapt the HR policy template.
- Name one lead organizer and one per group.
- Create a group for each department. Each group gets its own private links.
- Run all draws on the same day.
- Hold reveals by group, either on the same day or during team meetings. See reveal ideas.
- Collect feedback in January.
A timeline for five weeks
- Week 1: company announcement and policy, department organizers named.
- Week 2: groups created and sign-up open.
- Week 3: draws run, private links shared, wishlists open.
- Week 4: reminders and ship-by dates for remote staff.
- Week 5: reveals by group, thank-you and feedback.
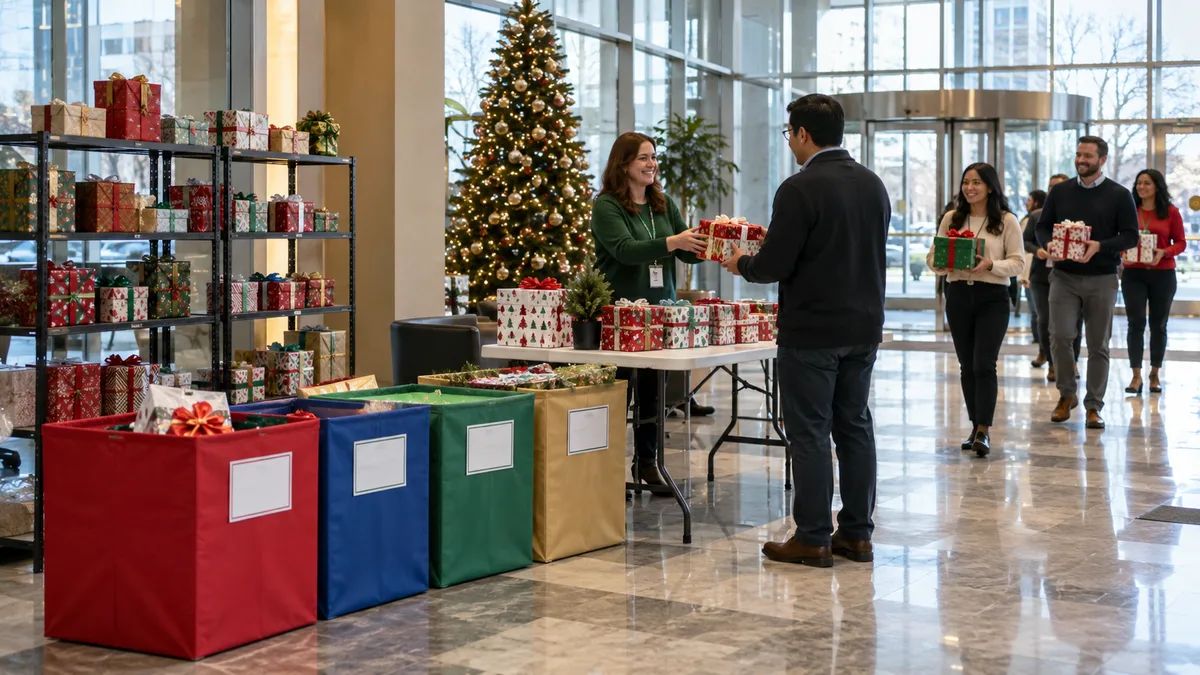
Gift drop-off at the lobby
- Set up one shelf or bin per department group, with a colored label, two weeks before the swap.
- Ask givers to leave gifts wrapped with the recipient's name on a tag, and no giver name.
- Name two volunteers per floor to carry gifts to desks, so the organizer does not.
- Keep a shelf of spare wrapped gifts for last-minute gaps; the organizer or a volunteer buys them.
- Remote staff ship to a named person at the nearest office, or receive an e-gift. See hybrid teams.
Who pays for what
- Gifts: each giver pays for their own gift unless the company decides otherwise.
- The event: the company may cover snacks and a room for the reveal.
- Organizer time: if it happens during working hours, get approval first. A law-firm article says a company will likely not be liable for workers’ compensation benefits after an incident at an event where attendance is optional, with no repercussions, and the company is not benefiting from it.3
- Shipping for remote staff: decide whether it is part of the $25.
What can go wrong with 100 people
Late sign-ups, missed gifts and confusion about which group someone belongs to are the three common problems. Give each person one link to one group, use a short deadline, and have each department organizer hold a small reserve of gift cards for last-minute gaps. Name a single company-level contact for questions, so people are not sent between organizers. If the company funds those reserve cards, remember they are taxable.
One group for all 100
Hollyhush groups are free for up to 50. If you want one group for everyone, up to 300 people, with a pasted list, emailed private links and a receipt for expenses, the paid Office plan covers it for a one-time fee per event. Most companies find that department groups work well and cost nothing.
For smaller groups, see Secret Santa for a large group and the office guides.
Create the first department group in a minute. Create your group, free
What the sources say
Section 132(e)(1) defines a de minimis fringe benefit as property or service so small in value that accounting for it is unreasonably or administratively impracticable, and the frequency of similar benefits is also considered.4
Sources
Each number in the text links to the passage it relies on.
- IRS Publication 15-B (2026), Employer’s Tax Guide to Fringe Benefits
Holiday or birthday gifts, other than cash, with a low fair market value (FMV).
- IRS Publication 15-B (2026), Employer’s Tax Guide to Fringe Benefits
Cash and cash equivalent fringe benefits (for example, gift certificates, gift cards, and the use of a charge card or credit card), no matter how little, are never excludable as a de minimis benefit.
- Marshall Dennehey: Party Time! Revisiting a Company’s Concerns During Social Activity Events (Defense Digest, Sept. 2021)
However, if employees are invited but are not obligated to attend, with no repercussions, and the company is not benefiting from the employee’s attendance at the event, then any incident that occurs will likely not result in the company being liable for workers’ compensation benefits.
- SHRM: Holiday gifts, prizes and parties can be taxable wages
Section 132(e)(1) defines a de minimis fringe benefit as any property or service the value of which is so small as to make accounting for it unreasonably or administratively impracticable. The determination of whether an item is de minimis must also take into account the frequency with which similar fringe benefits are provided by the employer to employees.
- IRS Publication 15-B (2026), Employer’s Tax Guide to Fringe Benefits
Any fringe benefit you provide is taxable and must be included in the recipient’s pay unless the law specifically excludes it.
Frequently asked questions
How do you run Secret Santa for 100 employees?
Split into department groups of 50 or fewer, set one budget and policy, and run all draws on the same day.
How much does Secret Santa cost for 100 people?
About $2,500 in gifts at $25 each. Hollyhush groups of up to 50 are free.
Can one group hold 100 people?
Free groups hold up to 50. The Office plan holds up to 300.
How long does it take to organize?
Five weeks from announcement to swap.
What if employees are in several offices?
Make a group per office and use e-gifts across locations.
Do we owe payroll tax if the company pays for gift cards?
Yes. Company-provided gift cards are taxable wages. Any fringe benefit is taxable and included in pay unless the law specifically excludes it,5 and cash equivalents such as gift cards, no matter how little, are never excludable as a de minimis benefit.2 Ask payroll before the company buys them.
Try it now
A draw takes about a minute. No signup, no email, a private link for everyone.
Create your group, free- Couples & exclusions
- Wishlists & anonymous questions
- Deletes itself in 60 days
Ready when you are
Make a draw in a minute. No signup, no email, private links for everyone.